Newsroom
Brokers write 81.6% of home loans. The harder question is who profits from it

- Oxcel Finance
- October 8, 2026
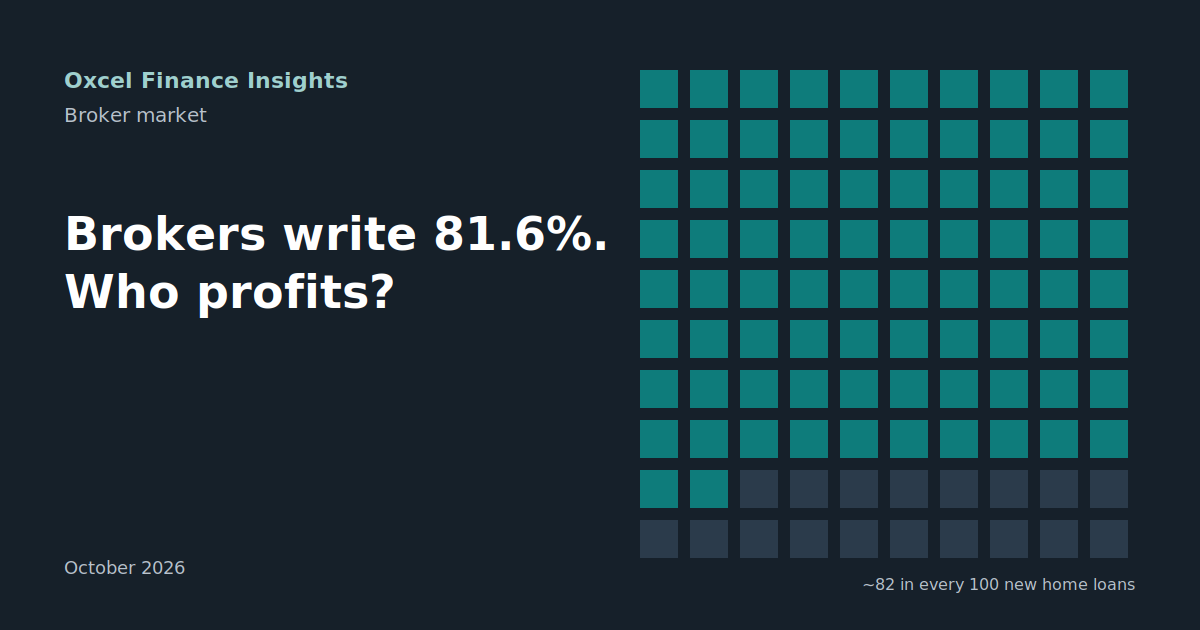
The MFAA's first State of Mortgage & Finance Broking Report confirms the broker channel has never been more dominant. But the same data shows clawbacks rising as fast as revenue, broker numbers growing faster than loan volumes in some segments, and a shrinking pool of mid-tier lenders. Market share is a channel win; profitability is decided business by business.
The headline numbers
Brokers facilitated 81.6% of new residential home loans in the June 2026 quarter, according to the MFAA. The association's inaugural State of Mortgage & Finance Broking Report, compiled by Cotality from data supplied by nine aggregators and covering calendar 2025, fills in the picture.
In 2025, brokers settled 838,815 home loans, up 17.2% on 2024. Settlement value rose 23.5% to $495.55 billion. Applications in a matched sample of eight aggregators rose 18.4% to 911,150. The broker-originated residential loan book reached about $1.17 trillion.
The broker population grew 9.1%, from 22,105 to 24,116. That is one broker for roughly every 904 Australian adults.
Loan growth outpaced broker growth — in 2025
On the 2025 numbers, loans settled (up 17.2%) grew faster than broker numbers (up 9.1%). On average, the channel became more productive.
Brokers should be careful about extrapolating that into 2026. Last year's growth came in a rising-price, falling-rate environment. This year the RBA has lifted the cash rate four times, national home values have fallen for six straight months, and ANZ reported that home loan applications fell 12% after the May federal budget announced negative gearing changes. More brokers chasing fewer, smaller deals is the risk to watch in 2026 data.
Revenue is up. So are clawbacks
Median gross broker revenue rose about 16% to $126,941. Median gross trail revenue per broker rose 18.7% to $77,894.
The less comfortable figure is the first industry-level clawback data. Median gross clawback per broker rose 16.5% to $11,442, based on five matched aggregators. That is roughly 9% of median gross revenue lost to clawbacks before any expenses.

The MFAA has linked clawback activity to competitive refinance markets. In practice, clawbacks hit hardest when clients refinance again within the clawback window, which is more likely when lenders compete aggressively on pricing and cashbacks.
Where the lending is going
Major banks remained the largest lender group, at 43.88% of reported new residential lending value through brokers in 2025, slightly down from 44.21%. Non-banks lifted their share from 6.5% to 7.2%. Major-bank-owned regional brands fell from 16.5% to 14.7%, and independent regional banks from 6.5% to 5.4%.

The lender panel is also narrowing. Suncorp Bank stopped taking new lending applications across broker and proprietary channels from 7 October 2026, as ANZ migrates Suncorp customers and plans to retire the brand by 2027. Final approvals and loan documents must issue by 27 October 2026, with settlement deadlines of 26 December 2026.
ANZ's own strategy, announced in October 2025, emphasises growing its proprietary mortgage sales force. Yet brokers still wrote 69% of ANZ's home loans in the six months to 31 March 2026, up from 67%. Lenders can invest in direct channels; they have not yet been able to bypass brokers.
Commercial and asset finance is the growth lane
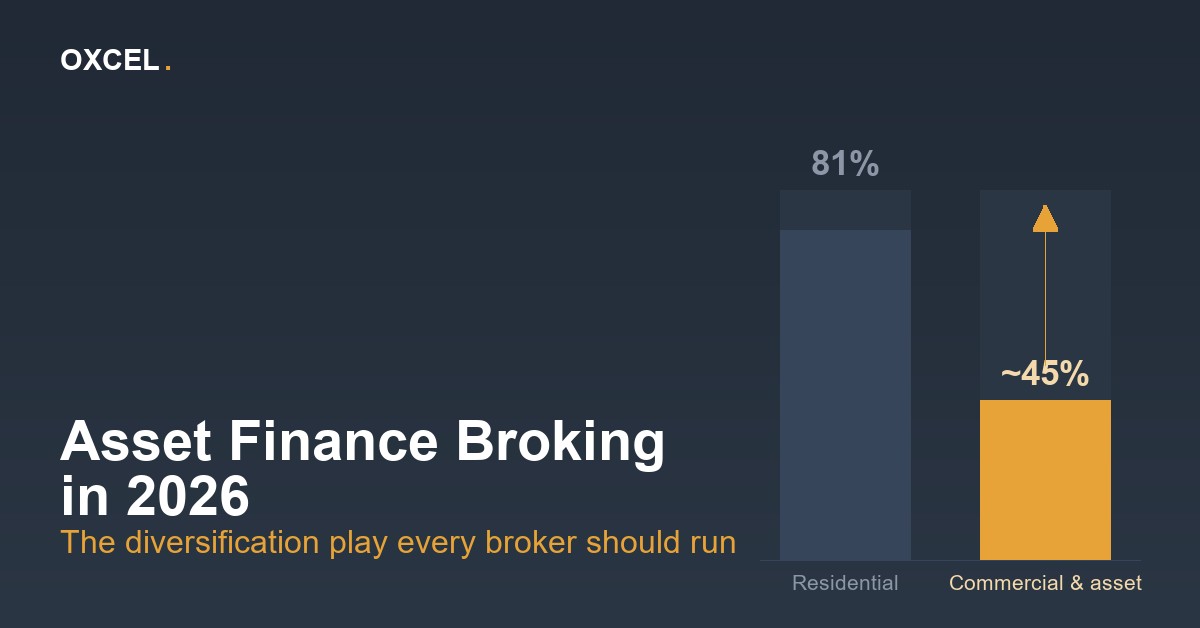
Commercial broker numbers rose 6.3% to 11,785. The value of commercial, business and asset finance settled by brokers jumped from $41.1 billion to $52.3 billion, roughly 27%.
That growth rate outpaced residential value growth. The MFAA has reported strong demand from members for commercial education, noting commercial lending is more complex than residential.
Key facts
- Broker share of new home loans: 81.6% (June quarter 2026, MFAA).
- Brokers: 24,116 at end of 2025, up 9.1%.
- Loans settled 2025: 838,815, up 17.2%; value $495.55 billion, up 23.5%.
- Median gross revenue per broker: $126,941, up ~16%.
- Median gross clawback per broker: $11,442, up 16.5%.
- Commercial/asset finance settled by brokers: $52.3 billion (2024: $41.1 billion).
- Suncorp Bank: new applications closed 7 October 2026.
What this means for brokers
Channel dominance does not guarantee individual profitability. Revenue growth was strong in 2025, but clawbacks are now a material cost line, and the 2026 market is materially weaker.
The clawback number should change how brokers think about refinance volume. A refinance that triggers a clawback 12 months later, or that leaves the client exposed to repricing, may be revenue that never stays.
Lender consolidation reduces choice. Fewer mid-tier lenders means less pricing tension and potentially weaker BID outcomes for some client profiles. Non-banks and specialist lenders are filling part of that gap.
Diversification is no longer optional for many brokers. Commercial and asset finance offer both growth and a hedge against a slower housing market, but they demand different skills and lender knowledge.
What brokers should do now
- Calculate your own clawback rate as a percentage of gross revenue and track it monthly.
- Check your pipeline for any Suncorp deals and confirm you can meet the 27 October approval and 26 December settlement deadlines.
- Review ANZ accreditation if you previously relied on Suncorp, as new lending through ANZ systems requires ANZ accreditation.
- Stress-test your 2026–27 income assuming lower settlement volumes, not 2025 growth rates.
- Pick one adjacent product line, such as asset or commercial finance, and build competence before chasing volume.
Oxcel perspective
The data supports what we see: brokers who combine residential with asset and commercial finance are more resilient when one market slows. The growth in commercial settlements is real, but so is the learning curve. Brokers should get training, lender access and support in place before they write their first complex deal.
General information only. This content does not constitute financial, credit, legal or tax advice. Finance products and lending criteria are subject to lender assessment and eligibility requirements.
Sources & further reading
- MFAA — State of Mortgage & Finance Broking Report 2026 (available to MFAA members), September 2026.
- Australian Broker — MFAA report lifts the lid on broking: broker income, commercial, clawbacks and more, 28 September 2026.
- Australian Broker — Suncorp no longer accepting mortgage applications, 6 October 2026.
- ANZ — ANZ prepares to welcome Suncorp Bank customers, September 2026.


















.png)