Newsroom
Switching Finance Aggregators: What Brokers Should Check Before Moving

- Oxcel Finance
- October 14, 2026
Before switching finance aggregators, review your current aggregation agreement and exit terms, confirm how your licensing or credit representative status will change, check each lender accreditation and transfer process, map live applications, trail, commissions and clawbacks, plan secure data and record migration, and test whether the new aggregator can support your business.
Switching aggregators is more than changing platforms. It can affect licensing, lender accreditations, technology, compliance, commissions, clients, data and your live pipeline, so treat it as a business transition. See how aggregation works for broader context.
Switching finance aggregators starts with the reason for moving
Define the problem you are trying to solve before comparing proposals. It may be lender access, asset or commercial capability, broker support, technology, compliance support, service levels, commercial terms, training or a broader business strategy issue.
Decide whether the problem could be resolved with your current aggregator or reflects a structural mismatch. Use comparing aggregators and choosing a finance aggregator to test the new option against your business needs.
Keep regulatory requirements, lender requirements, aggregator processes and contractual terms separate.

Trail entitlements, data access, restraints, commission arrangements and exit rights often depend on the relevant aggregation, commission and technology agreements, subject to applicable legal and regulatory requirements.
Review your agreement, notice requirements and licensing structure
Read your current aggregation agreement before signing a new one. Check the term, notice and termination requirements, fees, restraints, confidentiality, commission and trail provisions, clawbacks, client and data rights, technology access, intellectual property and branding.
The notice period and process for leaving an aggregator generally depend on your aggregation agreement; there is no single standard period that applies across all aggregation arrangements. Confirm how notice must be given, when it takes effect, what services continue during the notice period, whether you can lodge new applications, when CRM access ends and when lender relationships change. Where contractual rights or obligations are material or unclear, independent legal advice may be appropriate.
Before starting the transition, also confirm how your licensing arrangements will be affected. For regulated credit activities, a broker will generally need to hold an Australian Credit Licence (ACL) or be appropriately authorised under another licensee, such as as a credit representative, unless an exemption applies. The aggregator and the credit licensee may be the same entity, but they are not necessarily the same.
If you are a credit representative, establish when your current authorisation ends, when the new one begins, whether there would be a gap and what ASIC notifications are required. ASIC’s INFO 126 says a licensee must complete relevant background checks, confirm adequate training and current AFCA membership before authorisation, provide written notice and have systems to monitor and supervise the representative. For mortgage broker representatives, the recruiting licensee must also follow ASIC’s reference checking and information sharing protocol.
An authorisation given without AFCA membership has no effect. Do not engage in regulated credit activities during any gap between authorisations, and agree the timing of revocation and appointment with both licensees. Licensees must notify ASIC when they authorise, vary or revoke an authorisation.
Dual authorisation is only available in limited circumstances. ASIC explains that a person may be a credit representative of two or more licensees where each licensee consents to the other, or the licensees are related bodies corporate, with the other licensee’s details and consent included in the ASIC notification. Your contracts also need to permit it.
If you hold your own ACL, changing aggregator may not require a licence change, but check whether any licence details or obligations change.
Check lender accreditations before you move
Do not assume lender accreditations transfer automatically. For each important lender, confirm whether it is on the new panel, whether accreditation transfers or requires a fresh application, whether a release letter or new broker ID is needed, whether training is required, when portal access changes and what happens to existing applications.
Different lenders run different processes. Two examples, current as at 1 October 2026: CommBank residential asks for a clear release letter from the previous aggregator and an online transfer application through the new aggregator’s accreditation team, which it says can take up to two business days once submitted. Westpac commercial and equipment finance asks brokers transferring to another aggregator to complete the Westpac Group Transfer of Accreditation form with aggregator sign-off.
Other lenders differ and processes can change, so confirm each one directly. Some may restrict access to an existing pipeline during transfer. See broker accreditation for more detail.
Panel size alone is not the test. Compare the lenders that matter to your client base, including specialist, asset and commercial lenders. Do not substitute a lender simply because it is on the new panel; your obligations to clients, including the best interests duty for consumer home loans, still apply.
Protect live applications, settlements, trail and commissions
According to Broker Daily, lender processes can vary when a broker changes aggregator, and access to existing deals may be restricted during some transfers. Audit each live application by stage, record the relevant aggregator and lender ID, and confirm who will service it and what changes after termination. Do not assume applications can simply be moved.
Avoid re-lodging an application solely because your aggregation arrangement has changed. According to the OAIC and Equifax, a new credit application may result in another credit enquiry, while multiple applications can affect a borrower’s credit profile. Confirm the correct process with the lender and both aggregators before re-submitting.
For pending settlements, confirm how commission and settlement administration will be handled. Commission arrangements between lenders, aggregators and brokers can depend on contractual terms, so establish who receives the commission, what happens to loans settling after you leave and how outstanding payments will be reconciled.
Trail commission should be checked against the relevant agreements rather than assumed to transfer automatically. Confirm what remains payable after termination, whether trail rights can be transferred or assigned, any conditions affecting payment and how future clawbacks will be handled. Independent legal or accounting advice may be appropriate where the value is material.
Unpaid commission and clawbacks should also be checked against the relevant agreements. For consumer mortgage broking, the National Consumer Credit Protection Regulations include specific requirements for certain clawback arrangements, including limits on the repayment period and restrictions on passing clawback costs to consumers.
Treat client data and compliance records as a controlled migration
Client ownership is not a one-line answer. Neither “your clients are always yours” nor “the aggregator owns your clients” is a safe assumption; the position can depend on agreements, privacy obligations, CRM arrangements, licensing, referral arrangements, branding, restraints and client consent.
Client records can include identification, financial documents, credit information, fact finds, application notes, correspondence and compliance documents. Moving them is a sensitive information transfer, not simply an IT task.
Test your export before giving notice. Confirm what can be exported, in what format, how long access continues, what remains with the previous aggregator and whether documents, notes, emails, tasks, consents and compliance records are included.
Australian Privacy Principle 11 requires covered entities to take reasonable steps to protect personal information from misuse, interference, loss and unauthorised access, modification or disclosure throughout export, storage, transfer, upload and migration. APP 11 also requires information no longer needed to be destroyed or de-identified unless the law requires it to be kept.
Access does not automatically create a right to transfer or reuse information. Consider why it was collected, privacy notices and consents, contractual terms, the APPs and retention obligations, and get privacy or legal advice where the position is unclear.
Credit law requires certain records to be retained for set periods, so do not delete old files because you changed aggregator. Agree who retains the records, whether copies can be transferred, how they can be accessed later and who handles complaints relating to work completed under the previous licensee.
Plan technology, disclosures and the cutover
Map the affected systems, including CRM, application software, lender portals, document storage, e-signatures, compliance systems, commission platforms, reporting and integrations. Test new systems, validate migrated records and retain authorised access to historical records where appropriate. See technology in broking.
Review aggregator-provided templates, disclosure documents, calculators, marketing materials and workflows before carrying them across. Check what can still be used, what belongs to the old aggregator and what must be replaced, rebranded or updated.
If your licensee, credit representative status, aggregation relationship or remuneration arrangements change, client-facing disclosures such as your credit guide may need updating. Website content, email signatures, social profiles, advertising, business cards and automated messages should reflect the actual legal and commercial structure from the cutover date.
Referral partners may also need updated contact details, submission processes, agreements or disclosures. Share what they need without disclosing confidential contract terms.
Compare the new aggregator beyond the commission split
Compare relationship management, compliance and scenario support, accreditation assistance, lender escalation, technology, commission support, training and residential, asset and commercial capability. See what broker support an aggregator should provide.
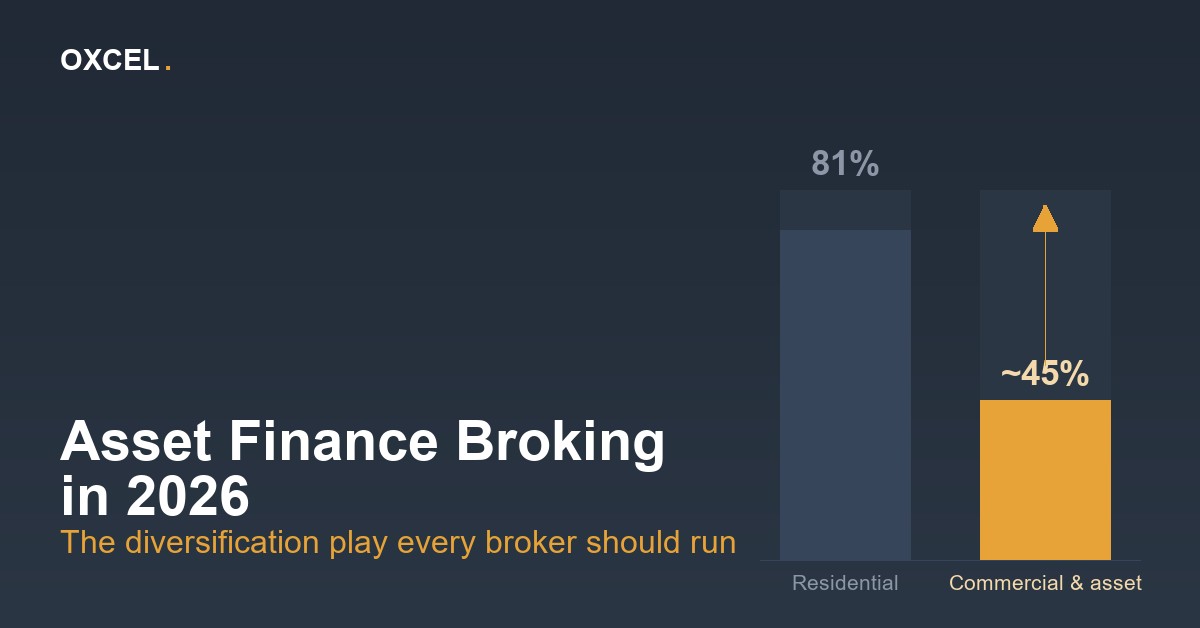
If asset or commercial finance matters to your business, test what lenders, expertise, systems, accreditation support and documentation sit behind the offer. The resources on how asset finance can help mortgage brokers diversify and preparing asset finance applications provide more detail.
Compare the full commercial model, not only the split. Review upfront commission, trail, aggregation, platform, compliance and transaction fees, technology costs, other charges, migration costs and transition disruption. If a sign-on incentive is offered, weigh it with repayment conditions, contract term, lender access, support, fees and exit rights; it should not be the deciding factor on its own.
Understand how you would leave the new aggregator before you join it. Review its agreement, notice requirements, trail and data provisions, exit process and ongoing access to records with the same care you apply to your current arrangement.
Broker transition checklist and key questions
Use one transition plan covering the main workstreams:
-
Review the current agreement, notice process, fees, restraints and post-termination obligations.
-
Confirm current and proposed ACL or credit representative structures, AFCA membership, authorisation timing and ASIC notifications.
-
Compare important lenders with the new panel and identify transfer, release, training, broker ID and portal requirements.
-
Audit every live application, approval and pending settlement and assign responsibility.
-
Reconcile unpaid upfront commissions, trail, clawbacks, fees and other outstanding payments.
-
Confirm client, data and record rights after termination.
-
Test CRM and document exports before access ends.
-
Plan secure transfer and retention of client and compliance records.
-
Confirm complaint handling for work completed under the previous licensee.
-
Test new technology and integrations before cutover.
-
Update disclosures, templates, branding and licence details where required.
-
Review referral arrangements and partner submission processes.
-
Confirm the residential, asset and commercial capability your business needs.
-
Review the new agreement, total commercial model and future exit terms.
-
Complete a post-transition check of lender access, pipeline, commissions, records and unresolved issues.
Key questions to put in writing before you move:
-
What notice is required, and when do systems and lender access end?
-
What happens to trail, unpaid commissions and future clawbacks?
-
Which lenders can transfer, which require fresh accreditation and which are not on the new panel?
-
How will live applications and pending settlements be handled?
-
What data and compliance records can be exported, retained or transferred?
-
What licensing structure will apply, who is the licensee and how will authorisation timing be managed?
-
What are the new aggregator’s total fees, support model, technology and relevant finance capabilities?
-
If I later leave, what does the new aggregator’s exit process look like?
There is no standard timeframe for changing aggregator. Timing depends on your contract, lenders, licensing, systems, pipeline and business size, so build your dates around the dependencies you have confirmed.
Frequently asked questions
| What happens to my trail if I change aggregator? |
| There is no universal answer. Trail treatment depends on the terms of your broker, aggregation and commission arrangements. According to the MFAA, brokers considering an aggregator should check whether they keep their trail if they cease trading or change aggregators, and under what circumstances trail could be lost. Review what remains payable after termination and how any clawbacks are handled, and seek legal advice if the position is unclear. |
| Do lender accreditations transfer when I change aggregator? |
| Not automatically. Lender accreditation transfers follow lender-specific processes. According to the MFAA, lender accreditation transfer processes can vary, which led it to develop a Lender Accreditation Transfer Form to help standardise residential accreditation transfers. However, not all lenders necessarily use the form, and some continue to use their own transfer or portal processes. Depending on the lender, a transfer may involve a release letter, transfer form, new application, broker ID or other accreditation steps. Confirm the requirements with each lender and both aggregators. |
| Can I take my client data when I leave my aggregator? |
| Not necessarily. Having access to client information does not by itself mean it can be transferred or reused for any purpose. According to the OAIC, personal information generally must be used or disclosed consistently with the purpose for which it was collected unless an exception applies. Check your agreements, privacy notices, client consents, retention obligations and the Australian Privacy Principles before transferring records. |
| What happens to live applications when switching aggregator? |
| Live applications should be checked individually before you switch. According to Broker Daily, some lenders may restrict a broker’s access to existing deals while an accreditation transfer is being processed. So, confirm with the lender and both aggregators whether each application can remain under its existing broker ID, who can continue servicing it, and whether any action is required during the transition. |
| How long does changing aggregator take? |
| There is no standard timeframe. According to Broker Daily, lender accreditation transfers can take several weeks in some cases, while data migration, technology changes and other transition requirements can add further time. Your own agreement may also contain notice or exit requirements, so build your timeline around the requirements that apply to your business. |
Evaluate Oxcel with the same framework
If Oxcel is one of the options you are considering, use the same framework to assess it. Before deciding whether Oxcel fits your business, understand how the transition would work in practice, including its aggregation structure, lender panel, accreditation transition process, residential, asset and commercial capability, technology, compliance support, onboarding, commercial arrangements and its own exit terms.
Talk to the Oxcel Aggregation Team
Sources:
Can you please remove the numbering in the beginning?
Australian Government (2009). National Consumer Credit Protection Act 2009. [online] Federal Register of Legislation. Available at: https://www.legislation.gov.au/C2009A00134/latest/text [Accessed 19 Oct. 2026].
Australian Government (2010). National Consumer Credit Protection Regulations 2010. [online] Federal Register of Legislation. Available at: https://www.legislation.gov.au/F2010L00631/latest/text [Accessed 19 Oct. 2026].
Australian Government (2020). Financial Sector Reform (Hayne Royal Commission Response—Protecting Consumers) (Mortgage Brokers) Regulations 2020: Explanatory Statement. [online] Federal Register of Legislation. Available at: https://www.legislation.gov.au/F2020L01189/asmade/2020-09-21/es/original/pdf [Accessed 1 Oct. 2026].
Australian Securities and Investments Commission (ASIC) (n.d.). ASIC reference checking and information sharing protocol. [online] ASIC. Available at: https://www.asic.gov.au/regulatory-resources/financial-services/reference-checking-directory-for-financial-services-and-credit-industries/asic-reference-checking-and-information-sharing-protocol [Accessed 19 Oct. 2026].
Australian Securities and Investments Commission (ASIC) (2017). Report 516: Review of mortgage broker remuneration. [online] ASIC. Available at: https://download.asic.gov.au/media/4213629/rep516-published-16-3-2017-1.pdf [Accessed 19 Oct. 2026].
Australian Securities and Investments Commission (ASIC) (2021). RG 271 Internal dispute resolution. [online] ASIC. Available at: https://www.asic.gov.au/regulatory-resources/find-a-document/regulatory-guides/rg-271-internal-dispute-resolution [Accessed 19 Oct. 2026].
Australian Securities and Investments Commission (ASIC) (2025). Responsible lending disclosure obligations: Overview for credit licensees and representatives. [online] ASIC. Available at: https://www.asic.gov.au/regulatory-resources/credit/responsible-lending/responsible-lending-disclosure-obligations-overview-for-credit-licensees-and-representatives [Accessed 19 Oct. 2026].
Commonwealth Bank of Australia (n.d.). CommBank residential brokers. [online] CommBank. Available at: https://www.commbank.com.au/home-loans/residential-broker.html [Accessed 1 Oct. 2026].
Westpac Banking Corporation (n.d.). Westpac Business Broker Accreditation. [online] Westpac. Available at: https://introducers.westpac.com.au/broker-accreditation [Accessed 19 Oct. 2026].
Office of the Australian Information Commissioner (OAIC) (2025). Chapter 11: APP 11 — Security of personal information. [online] OAIC. Available at: https://www.oaic.gov.au/privacy/australian-privacy-principles/australian-privacy-principles-guidelines/chapter-11-app-11-security-of-personal-information [Accessed 19 Oct. 2026].
Office of the Australian Information Commissioner (OAIC) (2025). Information on your credit report. [online] OAIC. Available at: https://www.oaic.gov.au/privacy/your-privacy-rights/credit-reporting/information-on-your-credit-report [Accessed 19 Oct. 2026].
Equifax Australia (2025). Soft vs. hard credit checks. [online] Equifax. Available at: https://www.equifax.com.au/personal/node/310 [Accessed 19 Oct. 2026].
Mortgage & Finance Association of Australia (MFAA) (2025). Choosing an Aggregator. [online] MFAA. Available at: https://www.mfaa.com.au/wp-content/uploads/2025/03/Choose-an-aggregator_Checklist_March2025.pdf [Accessed 19 Oct. 2026].
Campbell, J. (2025). Switching aggregators: A challenge that needs addressing. [online] Broker Daily. Available at: https://www.brokerdaily.au/broker/20314-switching-aggregators-a-challenge-that-needs-addressing [Accessed 19 Oct. 2026].
Campbell, J. (2025). Aggregators address concerns with changing groups. [online] Broker Daily. Available at: https://www.brokerdaily.au/broker/20348 [Accessed 19 Oct. 2026].
General Information
This article is general information current as at 14 October 2026. It is not legal, accounting, privacy or compliance advice. Your rights and obligations depend on your agreements and licensing structure; lender processes change, so confirm each one directly.












.png)